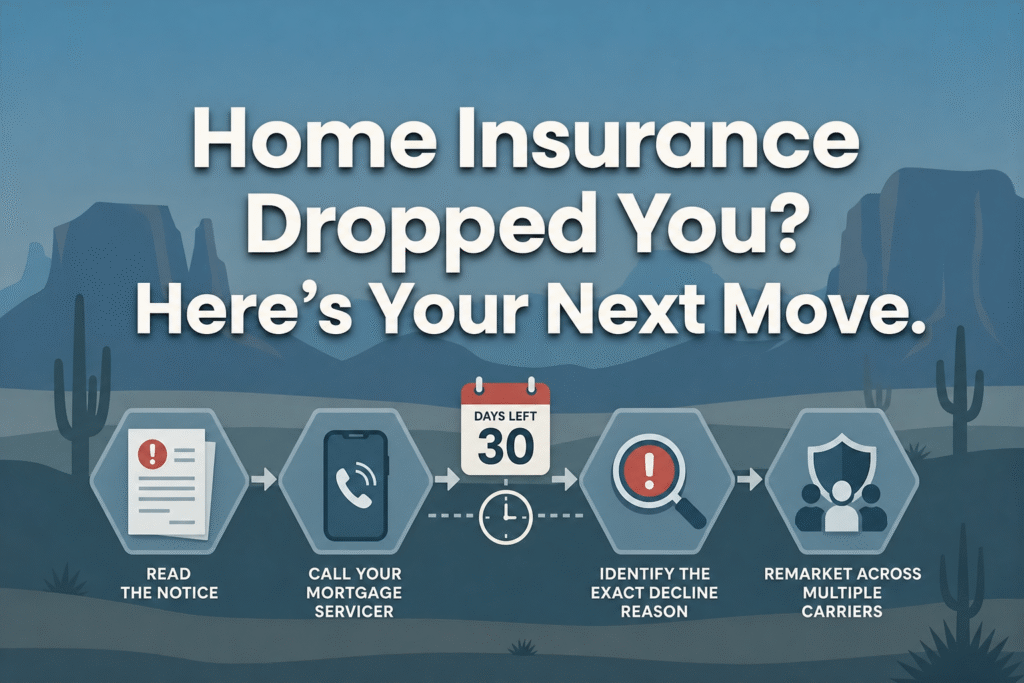
Your coverage is still in force until the termination date printed on the letter — a non-renewal does not end your policy the day you open the envelope. Use the window you have left in order: read the notice and find the end date and the stated reason, tell your mortgage servicer a replacement policy is in progress, gather your loss history and roof documentation, then start a multi-carrier remarket. Moving in the first week is what keeps you out of lender-placed coverage.
My home insurance company dropped me Arizona what do I do now — start by reading the notice
Three different letters get called “getting dropped,” and they carry three different levels of urgency. Before you do anything else, figure out which one is sitting on your kitchen counter.
Non-renewal means the carrier is letting your policy run to its natural expiration date and declining to write the next term. You are still insured today. Everything in that policy — dwelling, other structures, personal property, loss of use, liability — stays in force right up to the termination date. The carrier is simply closing the door on the renewal.
Cancellation is mid-term. The carrier is ending the policy before its scheduled expiration, usually for a narrow set of reasons such as non-payment of premium, a material misrepresentation on the application, or a change that substantially increases the risk. A cancellation notice gives you far less runway than a non-renewal, and it should move to the front of your to-do list the same day it arrives.
Conditional renewal is the one people misread most often. The carrier is offering to renew — but only if you do something first, or only on different terms. Replace the roof by a stated date. Remove the trampoline or install a compliant pool fence. Accept a higher wind and hail deductible, or a roof settlement change. A conditional renewal is not a decline. It is a negotiation with a deadline, and sometimes the condition is cheaper to satisfy than the remarket is.
Find three things on the letter and write them somewhere you will see them: the effective termination date, the stated reason for the action, and the policy number. Every conversation that follows — with your lender, with an agent, with an underwriter — begins with those three items. If the stated reason is vague, call the carrier and ask them to put the specific underwriting reason in writing. You are entitled to understand why, and the next carrier is going to ask.
How many days do I actually have before my coverage ends?
Count from today to the termination date on the letter, not from the date the letter was mailed. That number is your working window — and it is shorter than it looks, because you do not control most of the steps inside it.
A realistic remarket has moving parts that each take their own time. Quoting is fast. Underwriting review is not instant, especially when a decline reason has to be explained. Many Arizona carriers order an exterior inspection or an aerial image review before they will bind, and inspection vendors schedule when they schedule. Your mortgage servicer then needs to receive, process, and post proof of coverage, and that posting is rarely same-day. Subtract all of that from your calendar and the comfortable window shrinks fast.
Here is sane pacing for a standard notice period:
- Week one: read the notice, call the carrier for the specific reason, call your mortgage servicer, and open the remarket.
- Week two: assemble the documentation file — declarations page, loss history, roof age, updates, photos — and get it to your agent.
- Week three: review offers on coverage terms, not price alone, and schedule any required inspection.
- Week four and beyond: bind the new policy, send proof to the servicer in the format they require, and confirm it posted.
Waiting until the last two weeks is the single most common way Arizona homeowners end up with lender-placed coverage on their mortgage statement. The quote might still come together — but the inspection and the escrow posting will not.
Arizona law sets minimum advance notice requirements for non-renewal and cancellation, and those requirements differ by the reason for the action. Confirm the notice period that applies to your situation with the Arizona Department of Insurance and Financial Institutions rather than relying on a blog post, including this one.
Why did my Arizona home insurance company drop me?
These are the reasons that actually show up on Arizona non-renewal letters, and each one points toward a different re-placement path.
Wildfire exposure and brush scoring. Homes in or near the wildland-urban interface get scored on vegetation density, slope, and distance to fuel. A score can change without anything on your property changing, because the model or the imagery behind it was updated. This is a recognized statewide issue, not a one-off: a University of Arizona Cooperative Extension publication on wildfire and homeowners insurance non-renewals in Arizona notes that “the effects of wildfire on access to and affordability of homeowners’ insurance have become an increasing concern.” The pressure on Arizona homeowners has drawn institutional attention as well — a sitting U.S. senator has pressed insurance experts in a hearing on rising home insurance costs facing Arizonans.
Roof age and material. Many Phoenix-metro and Tucson homes built in the 1990s and early 2000s are now carrying original tile underlayment or shingles at the far edge of their service life. Underlayment matters more than the tile you see from the street, and underwriters know it.
Hail and monsoon claim history. Microburst wind, blown-in rain, and hail produce losses that cluster by neighborhood. A paid wind or hail claim can sit on your record for years.
Claim count regardless of size. Two or more losses in a rolling period will trigger a decline at some carriers even when the dollar amounts were small. Homeowners are often surprised to learn that a water mitigation call, a liability inquiry, or a claim that was closed without payment still appears in the loss database.
Water damage and slab leaks. Repeat water losses are the fastest route to a decline in Arizona, because carriers treat them as predictive rather than accidental.
Liability exposures. Pools without compliant fencing, diving boards, trampolines, and certain dog breeds each sit outside some carriers’ appetite.
Systems age. Federal Pacific or Zinsco panels, aluminum branch wiring, polybutylene supply lines, and water heaters past their expected life are common flags.
Occupancy changes. Vacancy, a tenant, or short-term rental use will void the assumptions behind a standard owner-occupied policy.
Appetite shift. Sometimes the house is fine, the record is clean, and the carrier simply pulled back from a ZIP code or a construction type. This is why a home with no losses on record still gets a letter.
Sort your reason into one of two buckets. A reason that follows the house — roof, brush score, plumbing, panel — can be fixed or documented away. A reason that follows the owner — claim frequency, a coverage lapse, a payment history — travels with you to the next application and has to be aged out or explained.
Call your mortgage servicer before they call you
Your carrier is going to notify your lender that the policy is terminating. That notification often reaches the servicer’s insurance department before you have finished reading your own letter. What happens next is automatic unless you interrupt it.
When a servicer cannot verify active coverage, it buys a policy on your home and bills you for it. This is called force-placed or lender-placed coverage, and homeowners are consistently shocked by two things about it. First, it typically costs dramatically more than a voluntary policy, because it is written without underwriting, inspection, or competition. Second, it is designed to protect the lender’s financial interest in the structure. It generally does not cover your personal property, it does not provide personal liability protection, and it does not pay for a place to live while the house is repaired. You are paying a premium that buys you very little.
The charge is added to your escrow account, which raises your monthly payment, often with a shortage spread across the following year on top of it.
Call the servicer in week one and keep the script short:
- “I received a non-renewal notice. My coverage is in force through [date]. A replacement policy is in progress through my agent.”
- “What is your deadline for receiving proof of new coverage before lender-placed coverage is ordered?”
- “What document do you accept — a declarations page, an evidence of insurance form, or a binder? What is the upload portal, fax, or email address, and what loan number formatting do you need?”
- “Please note the loan file that a replacement is pending.”
Write down the representative’s name and the date. If force-placed coverage has already been ordered, it can usually be removed retroactively once you submit proof of continuous coverage with no gap. Ask specifically for the force-placed premium to be refunded to escrow and for the account to be re-analyzed, then check the next two monthly statements to confirm the credit posted and your payment came back down. Servicers do correct this — but typically only after you send the document and follow up.
What to gather before anyone can quote you
A remarket moves at the speed of your documentation. Homeowners who hand over a complete file get offers in days. Homeowners who answer questions one email at a time get offers in weeks, and weeks are what you do not have.
Assemble this before your first quoting conversation:
- The declarations page from the expiring policy. This shows your dwelling limit, other structures, personal property, loss of use, liability, deductibles including any separate wind and hail deductible, and endorsements. It is the baseline the new policy gets compared against.
- The non-renewal or cancellation letter itself, with the stated reason visible. Do not hide it. The next underwriter will see the reason in the industry databases anyway, and an agent who knows the reason up front can route the file to a carrier that tolerates it.
- A complete loss history — date of each loss, cause, amount paid, and what was repaired or replaced. If a roof was replaced after a hail claim, that claim becomes an asset instead of a liability.
- Roof age and proof. The replacement invoice, the contractor’s warranty, or the city or county permit record. Note the material and whether the underlayment was replaced, not only the tile reset.
- Updates to the four systems underwriters care about — electrical panel and wiring, plumbing supply lines, HVAC, and water heater — with years and invoices where you have them.
- Proof of pool fencing that meets local barrier requirements, plus self-latching gate photos.
- Protective devices — monitored alarm, water shutoff sensors, surge protection, and any defensible-space or brush-clearance work if you are in a wildfire-exposed area.
- Current photos — all four exterior elevations, the roof from the ground or a ladder, the electrical panel with the cover open, and the water heater.
That last item deserves emphasis. A meaningful share of Arizona declines start with an aerial or satellite image: a stained roof, a visible patch, debris, or vegetation touching the structure. The image is a snapshot, sometimes years old, and it cannot tell the difference between tile discoloration from sun and a failing roof. Dated ground-level photos plus a roofer’s letter have reversed that kind of decline more than once. Documentation is the one part of this process entirely within your control.
The remarket: how an independent agency finds a carrier when yours said no
Here is the part the carrier that dropped you cannot do for you. They can tell you no. They cannot tell you who says yes.
An agency with appointments across multiple carriers runs a declined Arizona home through a matching process, not a price comparison. The decline reason is the key. Carriers weight risk factors very differently from one another: one treats roof age as close to a hard stop while another will write a 20-year-old tile roof with documented underlayment replacement; one declines on two losses in five years regardless of amount while another looks at cause and weather-related versus non-weather; one has pulled back from brush-scored areas statewide while another is still writing there with a defensible-space credit. A repaired roof with an invoice reads very differently to carrier A than to carrier B.
People ask which specific Arizona carriers still write after a roof-age decline, a hail claim, or a brush score. The honest answer is that the list changes — appetite guidelines get revised, ZIP code moratoriums go on and come off, and a carrier that took the risk last quarter may not this quarter. Publishing names in a blog post would mislead you within a month. Checking the live list against your specific reason is the daily transaction here. A captive agent, by contrast, represents one company; when that company declines, the only available answer is a referral somewhere else.
When offers come back, compare more than the premium:
- Coverage form — open-peril (HO-3 or HO-5) versus a named-peril form that covers less.
- Replacement cost versus actual cash value on the dwelling and on personal property.
- Roof settlement basis — a roof paid on actual cash value depreciates with age, and on an older Arizona roof that difference can be enormous at claim time.
- Wind and hail deductible — flat dollar or a percentage of the dwelling limit.
- Exclusions and sublimits — water backup, mold, service line, ordinance or law.
Expect the new policy to be structured somewhat differently from the old one. That is normal. What matters is that you choose the differences knowingly instead of discovering them during a monsoon claim.
What if no standard carrier will write my home?
Some homes are genuinely hard to place — a severe brush score, an original roof past its life with no budget to replace it yet, three water losses in four years. There is still a path.
Excess and surplus lines carriers exist for exactly this. They are described as non-admitted, which means their rates and forms are not filed with and approved by the state the way a standard carrier’s are. That flexibility is why they can write a risk nobody else will. It also means three things you should understand before you sign: the coverage form may be narrower than a standard homeowners form, the policy is generally not protected by the state guaranty fund if the insurer becomes insolvent, and surplus lines taxes and fees are added to the premium.
Other tools that open doors: a higher all-peril or wind and hail deductible, which moves the small losses off the carrier’s books and can turn a decline into an offer; a dwelling fire policy where a full homeowners form is unavailable; and splitting coverage, where one carrier writes the structure and liability is placed separately.
Treat these placements as a bridge, not a destination. One or two terms on a surplus lines policy while the roof gets replaced, the plumbing gets repiped, or the claims age past the lookback window is often enough to move the home back to a standard carrier afterward. Put a calendar reminder on the date your oldest claim ages off, and re-shop then.
If you reach the end of the voluntary market entirely, verify current residual-market and last-resort options with the Arizona Department of Insurance and Financial Institutions.
Four mistakes that burn the notice period
- Letting the policy lapse, even for one day. A gap in coverage becomes its own decline reason on the next application, and it is one of the few reasons that follows you rather than the house. Bind the replacement effective the day the old policy terminates — not the day after.
- Shopping on premium alone. The lowest quote on a declined home frequently gets there by putting the roof on actual cash value. On a 20-year-old tile roof in hail country, that is a decision you will feel during the first serious monsoon.
- Filing a small claim during the notice period. A new loss on the record while you are being remarketed can close doors that were still open. Pay small repairs out of pocket if you reasonably can, and talk it through with your agent before you report anything.
- Telling the mortgage servicer nothing. Silence is what triggers lender-placed coverage. One phone call in week one prevents a problem that takes months to unwind.
If you are holding a letter right now, the next step is simple: bring the non-renewal notice and your current declarations page to an independent agent and start the remarket while there is still runway on the calendar. No one can promise a particular carrier or a particular rate on a declined home — but the homeowners who start in week one end up with real choices, and the ones who start in week five usually do not.